
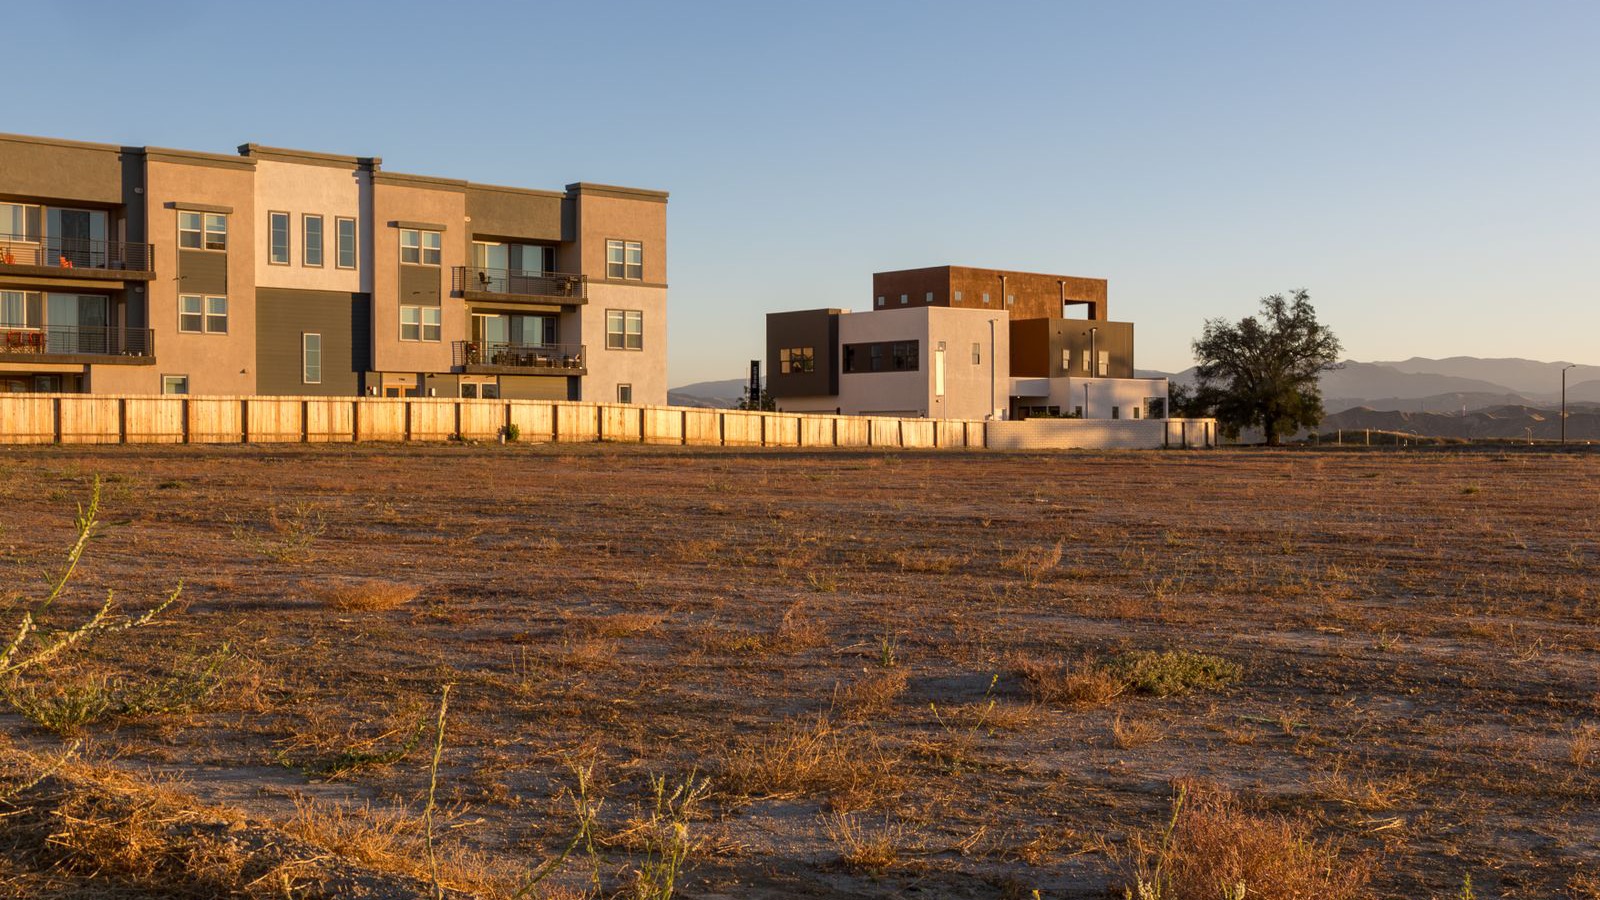
Land Tax On Vacant Land: Price the holding cost before the planning outcome
Most small developers price stamp duty carefully and then treat land tax as an afterthought. In New South Wales that habit is expensive, because land tax is a recurring cost that follows the site while you hold it.
Land tax is assessed on the unimproved value of the land you own at midnight on 31 December, and the assessment is not reduced for the part of the year you owned it. If you are holding a development site while you obtain a planning outcome, the bill can arrive well before the project makes a dollar.
What the charge actually is
According to Revenue NSW, you pay land tax when the combined value of all your non-exempt land exceeds the general threshold of $1,075,000. The general rate is $100 plus 1.6 per cent of the land value above that threshold, and there is a premium rate above $6,571,000. The thresholds and rates page confirms that the 2024-25 State Budget froze both thresholds for land tax years after 2024.
That freeze matters more than the headline rate. If values rise and the threshold does not, a holding that sits comfortably under the threshold this year can cross it after the next valuation, without you buying anything at all.
Why the threshold is a portfolio test, not a site test
The threshold is applied to your combined land value, not to each parcel in isolation. That is why Revenue NSW assesses an individual on 100 per cent of the land they own alone plus their interest share of anything they own jointly. Joint owners are treated as a single entity called the primary taxpayer, which means jointly held land attracts only one threshold between them.
A developer holding one site alone and a share of two others is not running three separate land tax positions. They are running one combined position, and the marginal parcel is what pushes them over.
The site test to run before you buy
Before you exchange on a development site in NSW, answer these questions on paper:
- What is the unimproved value, not the asking price? Land tax follows the Valuer General value of the land, excluding the buildings on it. A tired house on a good block can carry a land value close to the purchase price.
- What else do you already hold in NSW? Add the value of every non-exempt parcel you own alone, plus your share of every jointly owned parcel, and test that total against $1,075,000.
- How many full taxing dates will you cross? Land tax is charged for the full year following 31 December. A site held across two taxing dates is a two-year cost even if you sell in eighteen months.
- Does anyone in the structure have a different position? A joint venture partner, a company or a trust may be assessed differently from you as an individual. Ask the accountant to confirm who the taxpayer is before you model the number.
- Is any exemption actually available? Revenue NSW lists purchasing vacant land for construction that may not qualify for an exemption as a common cause of a first liability. Treat an assumed exemption as unconfirmed until it is documented.
A worked scenario
Suppose you already own one investment property with an unimproved value of $700,000, and you buy a development site with an unimproved value of $620,000. Neither looks threatening on its own. Combined, the holdings are $1,320,000, which is $245,000 above the general threshold. At the published general rate, the annual charge works out at $100 plus 1.6 per cent of $245,000, which is roughly $4,020 a year.
That figure is not the deal breaker by itself. What matters is that it repeats every year the site is held, that it is not reduced if you sell part way through the year, and that a revaluation can push it higher while your planning application sits in the queue.
The TPC deal lens
Test the deal like this: add the modelled land tax for every full taxing date the site will be held, and then ask whether the project still clears your margin hurdle. If the margin only works because land tax was left out, the margin is not real.
Two adjustments make this test more honest. First, run the numbers on the unimproved value rather than the purchase price, because they are not the same. Second, keep the total in the feasibility rather than in a contingency line, since a recurring annual charge is not an unexpected event.
What to do with the answer
- Record the unimproved value of every parcel in the ownership structure, with the valuation date.
- Total the holdings the same way Revenue NSW does, including your interest share of jointly owned land.
- Count the taxing dates the site will cross on your realistic timeline, not your optimistic one.
- Carry the annual charge in the holding cost forecast and re-test it after each valuation.
- Ask the accountant to confirm the taxpayer identity and any exemption before settlement, not after.
Key Takeaway
Land tax in NSW is a holding cost, not a purchase cost. It is assessed on unimproved value across your whole NSW portfolio, it is not pro rata, and the thresholds have been frozen. Model it for every full year you plan to hold, and confirm the taxpayer identity before you commit.
Your Turn
Take a site you are currently assessing. What is its unimproved value, and what is your combined NSW land value once every other parcel and joint interest is included?
Sources and boundaries
Sources checked 19 September 2026. Jurisdiction and limits: New South Wales only; land tax is a state tax and other states and territories use different thresholds, rates and assessment rules. Figures are those published by Revenue NSW as at the checked date and should be re-checked each land tax year.
- Revenue NSW — What is land tax?. Used for: General land tax threshold of $1,075,000, rate of $100 plus 1.6 per cent above the threshold, premium threshold above $6,571,000, taxing date of 31 December and the rule that land tax is not calculated pro rata. (Checked 19 September 2026)
- Revenue NSW — Land tax thresholds and rates. Used for: General and premium rate table and the 2024-25 State Budget freeze on the thresholds for land tax years after 2024. (Checked 19 September 2026)
- Revenue NSW — Individuals and joint owners. Used for: How individual assessments combine 100 per cent of solely owned land with your interest share of jointly owned land, and how joint owners are treated as a single primary taxpayer with one threshold. (Checked 19 September 2026)
- Revenue NSW — Understand your assessment notice. Used for: Joint owners may receive both an individual assessment and a separate assessment notice for the jointly owned land, and vacant land bought for construction may not qualify for an exemption. (Checked 19 September 2026)
This article is general education, not personalised planning, legal, financial, tax, privacy, safety or building advice. Requirements and outcomes vary by jurisdiction, site, contract, structure and circumstances. Check current information with the relevant authority and appropriately qualified advisers.
 Learn with Jason & AmyBuild practical small-scale property development skills with experienced mentors.Enquire now
Rate this article
Guest rating: select 1 star for poor or 5 stars for great. No account is required.
Leave a comment
Join the discussion. Your email address will not be published.
Frequently asked questions
Is land tax calculated only for the months I own the land?
No. Revenue NSW states that land tax calculations are not pro rata. The liability is assessed on land you owned at midnight on 31 December and is charged for the full year following that taxing date, so selling in February does not reduce the bill.
Does the threshold apply to each property separately?
No. The general threshold applies to the combined unimproved value of all your non-exempt land in NSW. Two or three parcels that look harmless on their own can push you over the threshold once they are added together.
I own a site with a joint venture partner. How is land tax assessed?
Revenue NSW treats joint owners as a single entity called the primary taxpayer, which means the jointly held land gets only one threshold. Each joint owner can also receive an individual assessment that includes their interest share of the jointly owned land plus 100 per cent of any land they own alone.
Does vacant land bought for a future build get an exemption?
Do not assume so. Revenue NSW lists purchasing vacant land for construction that may not qualify for an exemption as a common situation that creates a land tax liability. Confirm the position for the specific parcel before you rely on an exemption.
How should land tax be treated in a feasibility?
Treat it as a recurring holding cost for every full year the site is held, and model it on the unimproved value rather than the purchase price. Because the thresholds have been frozen, a site that is under the threshold today may cross it after a revaluation.
Loading comments…